We at AllTheProperties have experts waiting to help find you the best possible solution no matter your circumstances.
When you are buying and selling property, you will be in what is known as a 'property chain', which unless you are a cash buyer, buying a vacant property and not selling your current one, can be complicated and very frustrating.
A bridging loan is a short-term finance facility that can be used for any legal purpose and are commonly used for funding property transactions.
They can be used to 'bridge' a temporary gap in your finances before alternative funds become available or before a longer-term finance facility can be arranged.
Bridging loans can be set up very quickly, making them ideal for when an unexpected opportunity arises or if you have been let down by another lender or someone in your property chain. The lending criteria is also far more flexible than most standard finance options.
Bridging finance can be used to continue with your property purchase and maintain your position in a property chain if you’ve had a buyer pull out or been let down by a mortgage lender.
Whether you want to make some home improvements, build an extension, or build your own home, bridging finance can be used to fund any of these projects.
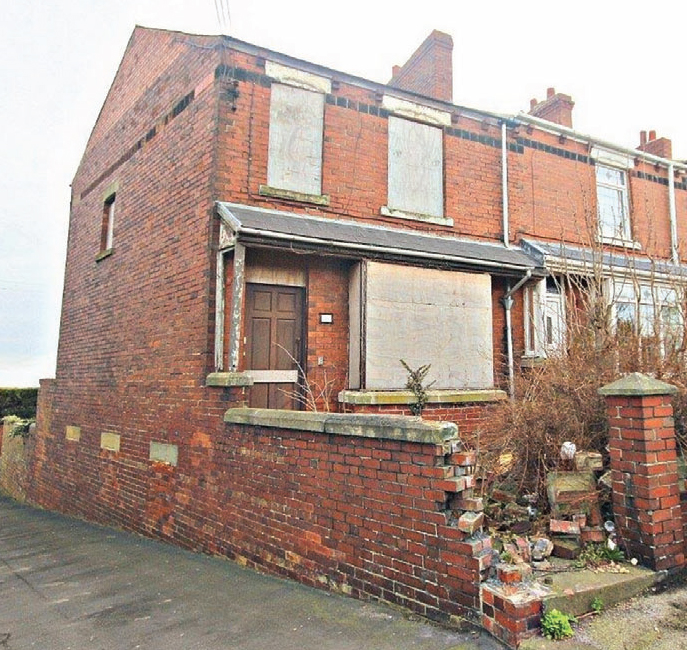
Some properties are deemed as unsuitable security for a traditional mortgage, making the property unmortgageable, and this is normally because the property is uninhabitable in some way. A property like this can only be purchased using cash, so it pushes buyers relying on a mortgage out of the market for this type of home.
However, bridging finance can be taken out and secured on an unmortgageable property and used to refurbish it.
When you purchase a property at auction, a deposit will be required on the day of the auction and the full purchase must normally be completed within a further 30 days. As it can be difficult to arrange a mortgage product within this timeframe, bridging finance can be used to complete the purchase instead.
If you’re coming to the end of an existing bridging loan term and your planned exit strategy has fallen through, you can take out a re-bridge to pay off your current finance facility and to give you more time to complete your project/sell your property.
Bridging finance can be used to fund the purchase of another property.
Properties can be in a poor state of repair or even unsuitable for traditional mortgage lending.
Bridging finance is designed and intended to be a short-term funding solution, so having a clear exit strategy in place is vital. The two most common exit strategies are either the sale of a property or development project, or refinancing with a longer-term facility like a mortgage.
If your planned exit route is refinancing, then you need to make sure that this finance option will be available before you take out the bridging loan to ensure that you will be able to repay the bridge as planned.
Bridging loans can be set up very quickly – sometimes in just a few days. This is ideal if you’ve been left in a difficult situation and need access to funds quickly.
The lending criteria for bridging finance is far more flexible than for traditional finance facilities like mortgages and secured loans as they are not so income or credit history dependent.
No monthly repayments will be required throughout the full term of the loan as everything is repaid at the end. If you would prefer to pay back the interest monthly, then there are plans which allow for this.
As you do not have to make any monthly repayments, no proof of income is required. This makes bridging easily accessible to those who are self-employed.
You can clear your bridging loan at any point during the term and you won’t be charged any penalties or fees. Interest is charged daily and only up until the day you clear the loan even if you clear it before the end of term (after the first 30 days).
For the price of a couple of coffees a week you can feature your company on
The Biggest FREE For Sale And To Let Property Search Engine In The World